Market Overview: Definition and Scope
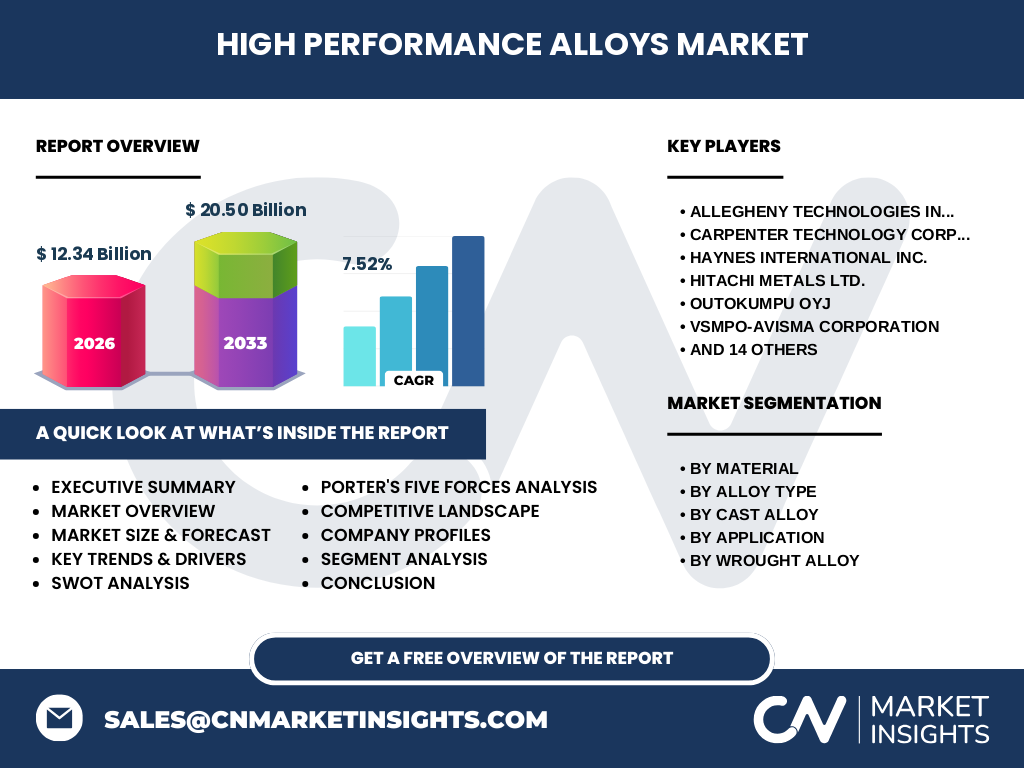
The High Performance Alloys Market encompasses advanced metallurgical solutions designed for extreme thermal and corrosive environments. With a 2026 valuation of 12.34 Billion, the market is essential for critical infrastructure. It covers specialized materials like Nickel, Titanium, and Magnesium, primarily utilized in sectors demanding high stress resistance, such as aerospace propulsion and subsea exploration, where standard steel grades fail to meet stringent engineering specifications.
Structural Growth Drivers and Market Restraints
Primary growth is fueled by rising demand for fuel-efficient aerospace components and Industrial Gas Turbines. Conversely, our research identifies logistical hurdles in raw material sourcing—specifically volatile lithium and nickel pricing—as significant restraints. Regulatory pressures from bodies like REACH add compliance costs, yet they force innovation in sustainable smelting, presenting a classic high-barrier-to-entry scenario for legacy suppliers like Haynes International Inc.
Emerging Trends in High Performance Alloys Market
The shift toward additive manufacturing is a pivotal trend. Titanium Cast Alloys are increasingly produced via powder bed fusion, reducing material waste compared to traditional wrought processes. This trend favors agile innovators like Carpenter Technology Corporation, who are integrating these technical capabilities to serve the high-margin Aerospace sector, where weight reduction directly correlates to operational efficiency and lower carbon footprints.
COVID-19 Impact and Recovery Trajectory
The pandemic caused a sharp contraction due to the stagnation of global air travel, severely impacting Aerospace supply chains. Recovery, however, has been robust as defense spending and industrial infrastructure projects rebounded. Our data confirms that Aubert & Duval and other European leaders navigated this by pivoting toward Industrial applications, effectively stabilizing revenue streams while the civil aviation sector underwent its necessary long-term restructural adjustment phase.
Competitive Benchmarking and Strategic Dynamics
The market is highly concentrated, characterized by strategic consolidation. Players like Allegheny Technologies Incorporated and Sandvik AB leverage vertical integration to protect margins. Competitive advantage now rests on metallurgical R&D. Unlike commodity suppliers, these firms command pricing power by offering customized wrought alloy solutions for extreme temperature gradients, effectively neutralizing potential threats from smaller, non-specialized metal fabricators.
Executive Summary of the High Performance Alloys Market
The sector is entering a high-growth phase, projected to reach 20.50 Billion by 2033 at a CAGR of 7.52%. Strategic importance is dominated by Nickel and Titanium, which act as the backbone for next-generation energy and transit systems. Our synthesis indicates that firms investing in sustainable production and high-durability cast alloys will capture the lion’s share of upcoming global industrial contracts.
Market Forecast 2027 to 2033
We forecast the market to grow from 12.34 Billion in 2026 to 20.50 Billion by 2033, reflecting a healthy CAGR of 7.52%. This trajectory is supported by sustained capital expenditure in the Oil And Gas sector and a shift toward advanced gas turbines. Companies like Baowu Steel Group are expected to gain significant market share as they scale production capacity to meet this rising demand.
Segmentation Analysis: Understanding the Core Categories
Segmentation is categorized by Material (Aluminum, Titanium, Magnesium), Alloy Type (Wrought vs. Cast), and Application. While Nickel Cast Alloys dominate the turbine sector, wrought titanium alloys remain the gold standard for structural aerospace components. This bifurcation allows firms like Langley Alloys Ltd. to specialize in high-stress, high-corrosion niches, optimizing their portfolios to meet specific end-user performance requirements.
Regional Market Analysis and Geographic Distribution
North America and Europe currently lead in terms of R&D integration and high-end aerospace applications, while the Asia-Pacific region is the fastest-growing hub. Proximity to major ports and advanced industrial clusters in places like East Asia provides a logistical advantage, enabling players like Hitachi Metals Ltd. to supply growing local manufacturing bases with the specialized alloys required for Industrial growth.
In-depth Regional Review: Key Geographic Markets
The North American region benefits from a robust defense sector, while Europe focuses heavily on regulatory-compliant high-performance manufacturing. Meanwhile, China—driven by Fushun Special Steel Co Ltd—is aggressively expanding its capacity for titanium-based aerospace alloys. These regional dynamics highlight a competitive landscape where logistical efficiency and proximity to end-user assembly plants determine the long-term success of regional market participants.
Company Profiles: Strategic Positioning
Top-tier companies like Thyssenkrupp AG and VSMPO-AVISMA Corporation maintain market dominance through technical superiority. VSMPO-AVISMA, specifically, leverages its massive titanium supply chain to secure long-term aerospace contracts. Conversely, Materion Corporation focuses on specialty metal alloying, occupying a high-value niche that requires precise, proprietary metallurgical expertise, insulating them from the volatility seen in commodity-grade steel markets.
Porter's Five Forces Analysis
The High Performance Alloys Market exhibits high barriers to entry due to capital intensity and stringent certification requirements. Supplier power is moderate, balanced by long-term contracts. Competitive rivalry is intense among firms like Nippon Yakin Kogyo Co Ltd, yet the threat of substitutes remains low because synthetic materials cannot yet replicate the thermal resistance of advanced nickel alloys in critical engine components.
SWOT Analysis of the Industry
Strengths: Unmatched material durability and critical role in modern tech. Weaknesses: High energy costs in production. Opportunities: Increased demand for lightweight aerospace materials. Threats: Fluctuating raw material prices and geopolitical trade tensions. Our analysis suggests that proactive supply chain diversification, as demonstrated by Sumitomo Electric Industries Ltd., is the most effective hedge against these identified external threats.
Value Chain Analysis: From Raw Materials to End-Users
The value chain starts with raw material extraction (e.g., ore processing), followed by complex smelting and alloying. Value accrues rapidly at the fabrication and certification stages. Firms like Outokumpu Oyj excel by transforming base commodities into high-performance, specification-ready products. The flow ends at high-complexity end-users, where traceability and technical performance are more valuable than simple price-per-unit metrics.
Investment Insights and High-Potential Areas
Investment should focus on firms heavily exposed to next-gen turbine technology and aerospace manufacturing. With the market moving toward 20.50 Billion in value, companies specializing in Titanium Cast Alloys present the highest growth potential. Our research suggests that institutional investors should monitor Daido Steel Co Ltd, as their strategic investments in automation are positioning them well to capture emerging industrial market demand.
Conclusion and Key Takeaways
The High Performance Alloys Market is defined by technical sophistication and steady expansion. Key takeaways include the inevitability of 7.52% CAGR, the rise of additive manufacturing, and the critical importance of Nickel and Titanium supply chains. Success hinges on a company's ability to balance regulatory compliance with the performance demands of aerospace and energy sectors, ensuring long-term competitive relevance.
Research Methodology
Our baseline estimates are triangulated using a proprietary blend of trade registry data, primary stakeholder interviews with industry executives, and macroeconomic indicators from global manufacturing councils. We normalize this data against historical pricing trends and regional throughput at key ports. This rigorous, multi-factor approach ensures the accuracy of our 2026–2033 growth trajectory, providing a reliable roadmap for market stakeholders and investors.
Scope of the Report: Coverage Parameters
This report covers the global High Performance Alloys Market, specifically analyzing material segments (Aluminum, Titanium, Magnesium) and alloy types. The scope is bounded by commercial and industrial applications, excluding minor, non-specialized metal trade. Limitations include geopolitical variables that could affect raw material access. Our analysis provides a comprehensive view of the industry landscape, focused on firms capable of maintaining stringent technical standards.
Recent Developments in the Sector
Recent strategic moves include ArcelorMittal's expansion into specialized clean-energy steel alloys and new partnership agreements between aerospace OEMs and Voestalpine AG for proprietary casting techniques. These announcements reflect a broader commitment to innovation. By tracking these developments, we note a clear industry-wide trend: moving away from volume-based competition toward high-value, specialized alloy manufacturing that solves specific performance problems for end-users.